he management board of TAQA Morocco met on September 8, chaired by Abdelmajid Iraqui Houssaini, to approve the accounts at June 30. The operator of the thermal units at Jorf Lasfar reports consolidated revenue of 5,088 million dirhams against 5,379 a year earlier, gross operating profit of 1,660 million, near flat, and net profit attributable to the group of 462 million against 437, up 5.8%. The half would turn out to be one of maintenance: a twenty-five-day minor overhaul on Unit 3 and scheduled inspections on the others brought the availability rate of Units 1 to 6 down from 91.7% to 86.6%, for output of 6,684 gigawatt-hours, while the dollar-dirham parity worked against the group.
Investment reaches 515 million dirhams against 210 in the first half of 2025, consolidated net debt comes back to 4,621 million, down 10.1%, and gearing to 36% against 38%. Behind those figures the group is changing shape: the reorganization approved on July 17 by the supervisory board moves it toward a holding company steering four businesses, desalination, renewable energy, natural gas, and low-carbon water and energy transport infrastructure. By 2030 that portfolio represents a projected capacity of 8.6 gigawatts, of which 4.8 come from renewables, alongside significant desalination and water-transport capacity. The company, listed on the Casablanca Stock Exchange since December 2013 and long identified with the single plant at Jorf Lasfar, will have turned itself, if that calendar holds, into an operator of water as much as of electricity.
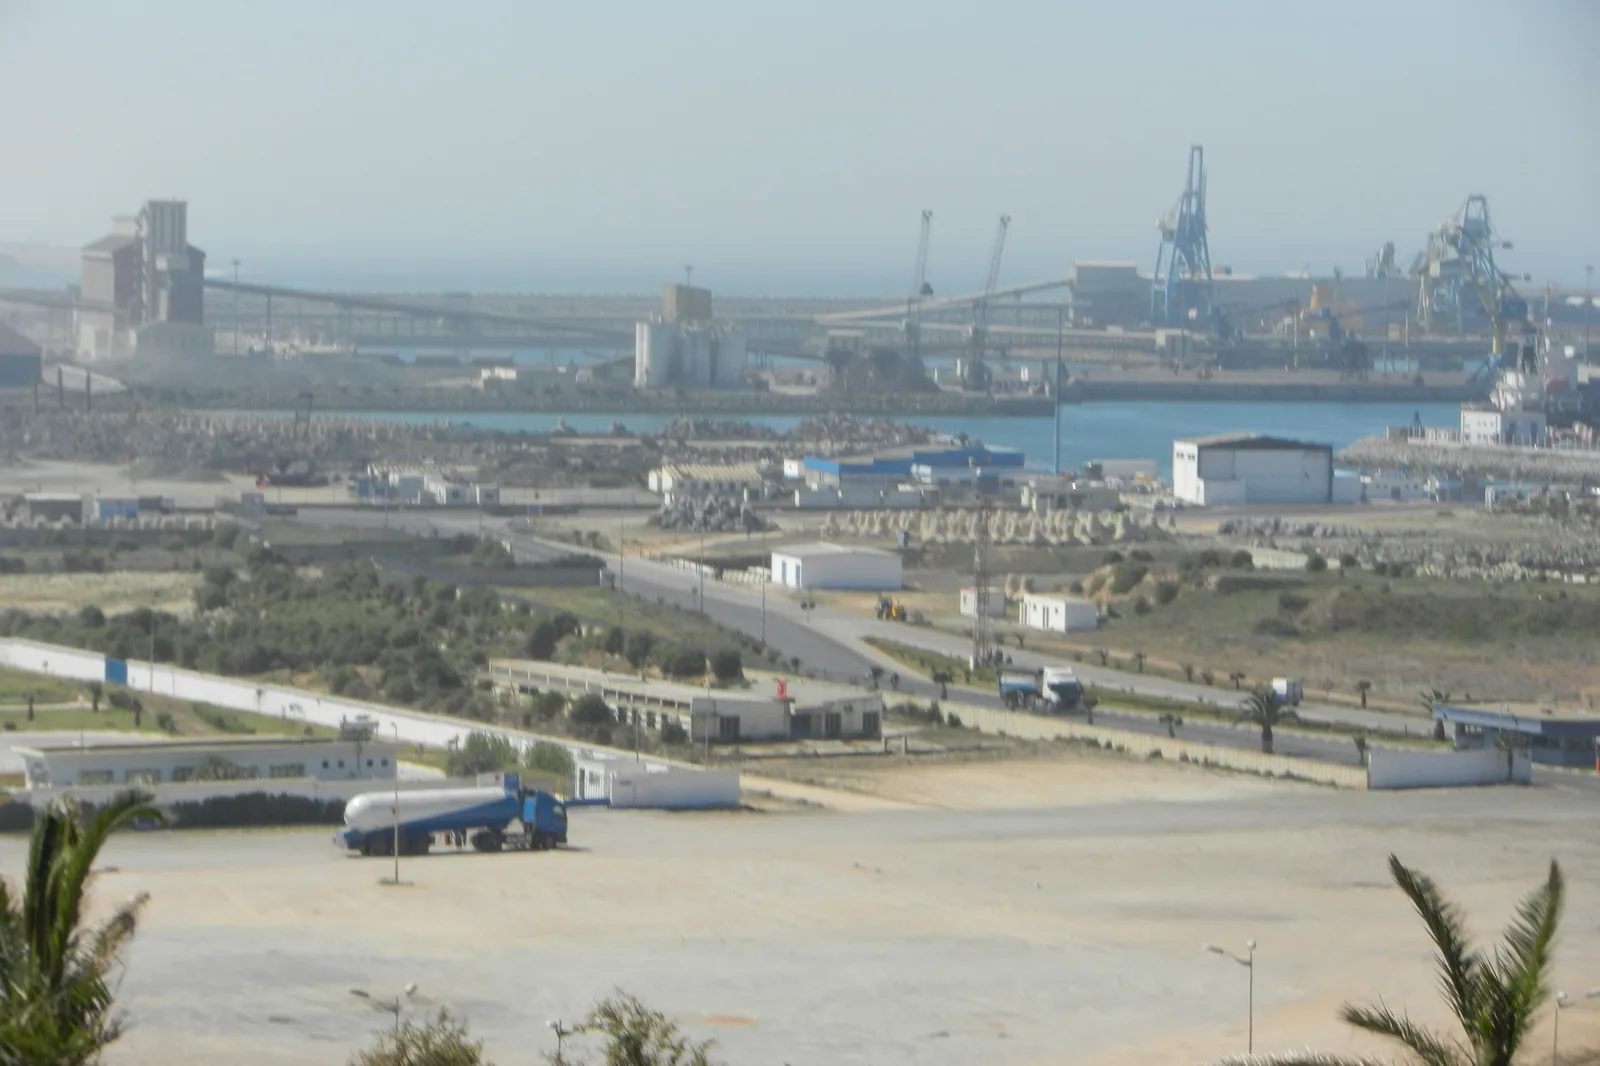
Photo: JOSIANE P., CC BY-SA 3.0.
TAQA Morocco - Communiqué de presse — Résultats au 30 juin 2026