The agency S&P Global Ratings maintained the issuer rating of OCP at BBB-, stable outlook, at the end of a bulletin published on November 19, according to a communique of the group dated November 20. Its stand-alone credit profile remains at bbb-, in the Investment Grade category.
The agency attributes the pressures of 2026 to a global market shock. Since March, the conflict in the Middle East disrupts the supply of sulfur, whose price exceeded 1,050 dollars per ton this summer, against 100 to 300 dollars on average in 2023 and 2024.
S&P thus estimates that the adjusted EBITDA margin of the group, of 35% at the end of 2025, would settle around 15% over the 2026 fiscal year, and that the adjusted debt/EBITDA ratio would rise temporarily to 7.6 times.
In order to preserve its liquidity, OCP brought its investments down to 22.7 billion dirhams in 2026, against an average of 35 billion, and raised 20 billion dirhams of hybrid capital. Its management also committed to cancel the dividend payable in 2027, subject to the approvals of its governance bodies.
The agency projects a margin of 23 to 25% in 2027, then above 30% from 2028, with the normalization of the costs of sulfur and of ammonia.
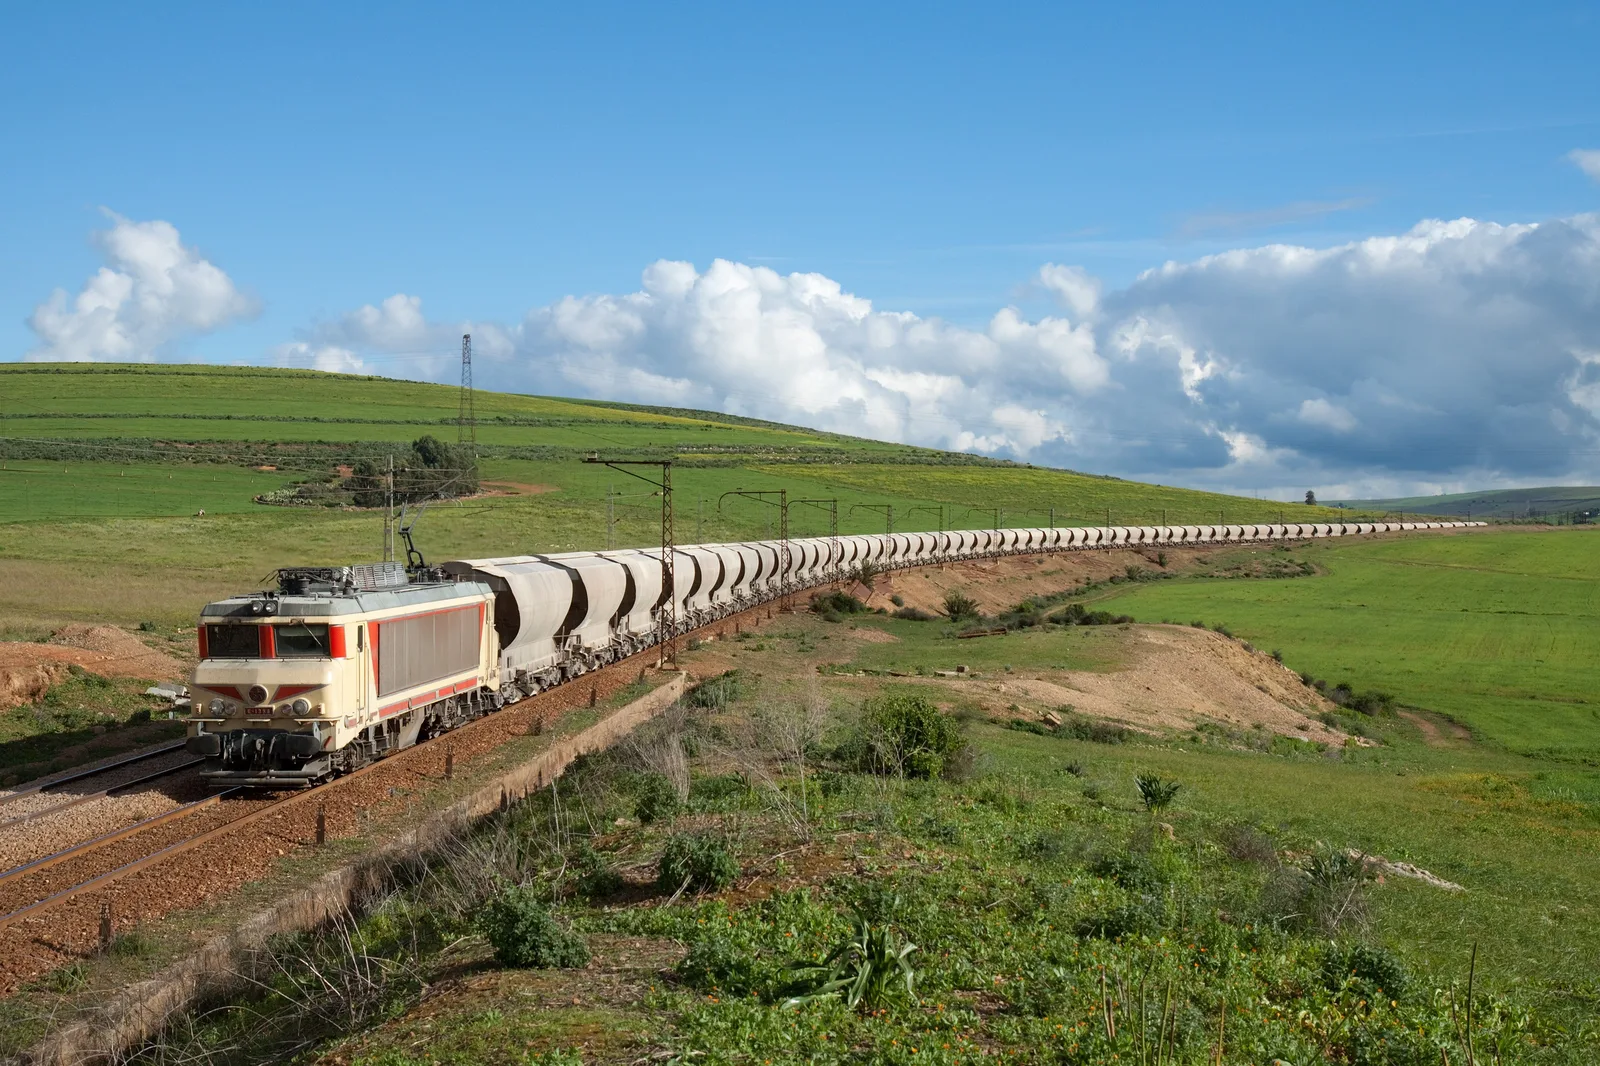
Photo: Kabelleger / David Gubler, CC BY-SA 3.0.
OCP - S&P maintient la notation Investment Grade d’OCP à BBB-/Stable et souligne sa discipline financière